
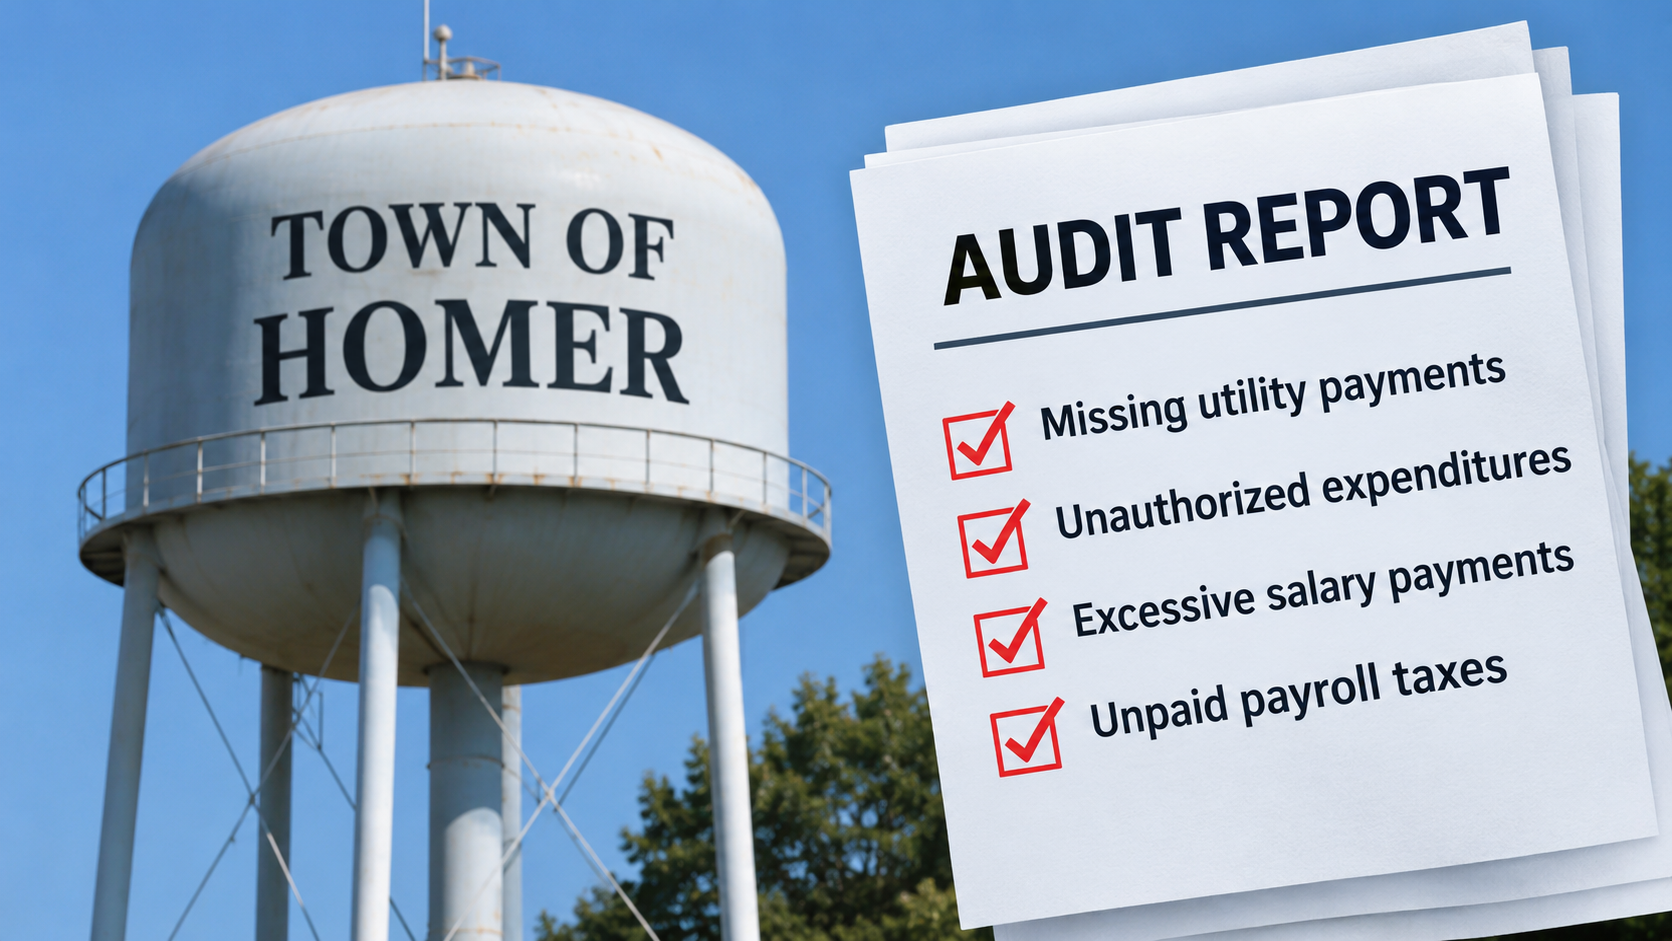
An investigation by the Louisiana Legislative Auditor’s Office has uncovered numerous financial irregularities in the Town of Homer, including missing utility payments, unauthorized expenditures, excessive salary payments, and hundreds of thousands of dollars in unpaid payroll taxes and penalties.
The findings were included in an investigative audit released Monday, November 9, following concerns raised by the town’s fiscal administrator, who was appointed in July 2024.
Among the findings, auditors determined that the town treasurer failed to deposit $16,769 in cash collected from utility customers between March and August 2024 into the town’s bank account.
Auditors also identified $4,475 in credits applied to the personal and business utility accounts of the treasurer’s landlord between July 2022 and March 2024. Investigators found no corresponding payments from either the landlord or the treasurer to account for those credits.
The investigation also revealed that $81,869 was improperly transferred from customer utility deposits into the town’s payroll account in December 2021 and June 2022. Those funds, which originated from customer deposits, were used to pay town employees.
In another finding, auditors determined that the town treasurer received $88,056 in salary and overtime payments exceeding the amount approved by the Town Council. Those payments occurred between January 17, 2019, and November 26, 2024.
The audit also raised concerns about the mayor’s handling of town finances and expenditures.
According to auditors, the mayor increased water and sewer rates without conducting a public hearing or obtaining approval from the Town Council.
Additionally, the mayor authorized $1,049,639 in expenditures from American Rescue Plan Act funds without first securing council approval. The federal funding was provided to local governments as part of pandemic-related economic relief efforts.
Auditors also found that the town failed to remit $253,086 in state and federal payroll taxes during 2023 and 2024. That failure resulted in an additional $96,806 in fees and penalties.
The findings raise questions about the town’s financial oversight, accounting practices, and compliance with requirements governing public funds.
The audit identifies financial irregularities and failures to follow required procedures but does not, by itself, establish criminal wrongdoing.